The Simple Budgeting Method That Can Transform Your Finances
Ask anyone for a simple way to budget and there’s a good chance they’ll mention the 50/30/20 rule. It’s easy to remember, needs only a calculator, and gives you an instant sense of whether your money is roughly in the right places. But it was designed for American households in the mid-2000s, and anyone trying to apply it to a Mumbai rent, a home loan EMI in Bengaluru or a joint family budget in Lucknow quickly runs into questions the rule doesn’t answer.
This guide explains the 50/30/20 rule properly: where it came from, exactly what belongs in each category, how it works on Indian salaries at different income levels, and what to do when your needs take more than half your income. It also covers popular variations such as 60/20/20 and 70/20/10, and the grey areas where most people get stuck. If you’re brand new to budgeting, start with our step-by-step guide to budgeting for beginners and come back here to choose your split.
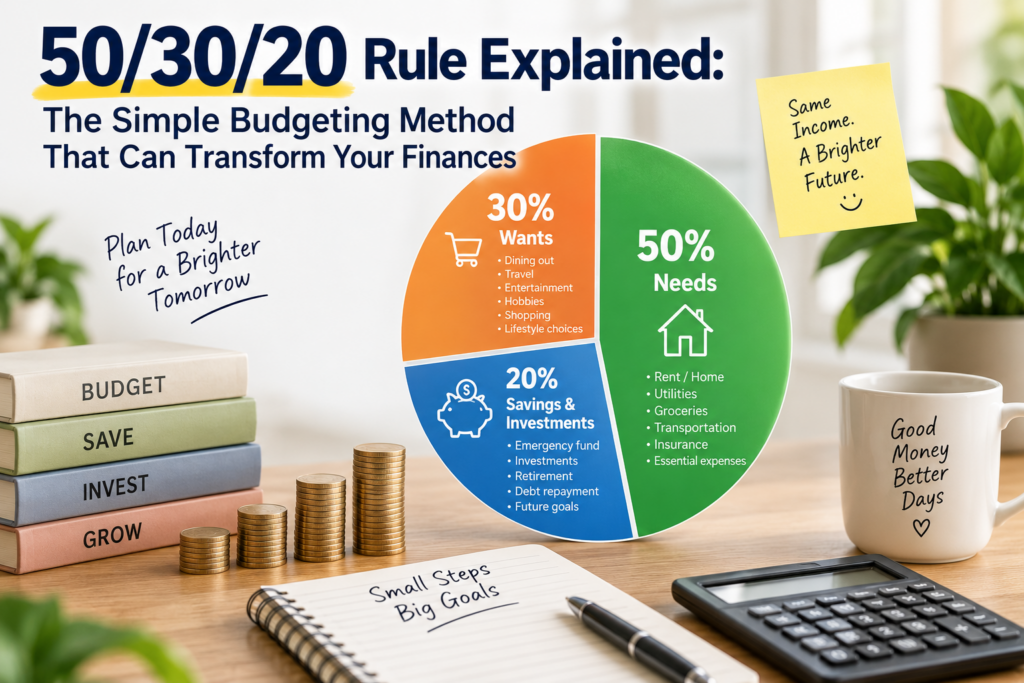
Quick Answer: The 50/30/20 rule says to divide your monthly take-home pay into 50% for needs (rent or EMI, groceries, utilities, insurance, transport and minimum loan payments), 30% for wants (eating out, shopping, entertainment, travel) and 20% for savings and extra debt repayment (emergency fund, SIPs, prepaying loans). It’s a starting guide, not a law: in high-rent cities, a 60/20/20 or 70/20/10 split may be more realistic at first, as long as savings are automated and you work back towards saving at least 20%.
Table of Contents
- What Is the 50/30/20 Rule?
- Why the Rule Works
- The 50%: Needs
- The 30%: Wants
- The 20%: Savings and Debt Repayment
- Need or Want? The Grey Areas
- 50/30/20 Examples on Indian Salaries
- When Needs Take More Than 50%
- Variations of the 50/30/20 Rule
- How to Start Using the 50/30/20 Rule
- Pros, Limitations and Common Mistakes
- Frequently Asked Questions
- Conclusion
- Sources and Further Reading
What Is the 50/30/20 Rule?
The 50/30/20 rule is a simple way to divide your income into three broad buckets. It was popularised by Elizabeth Warren and her daughter Amelia Warren Tyagi in their 2005 book All Your Worth: The Ultimate Lifetime Money Plan, where they called it the “balanced money formula”. The idea was to give families a quick check on whether their spending was in balance, without tracking every rupee in dozens of categories.
An important detail that many summaries miss is that the percentages apply to take-home pay, after taxes, not to gross salary. For a salaried Indian, that means the amount credited to your bank account after TDS, your EPF contribution and other deductions on your payslip, not your CTC. Using the wrong base is one of the most common reasons the rule seems not to work.
Why the Rule Works
The 50/30/20 rule works for beginners because it’s simple enough to use without an app or spreadsheet, and because it builds savings in from the start rather than treating them as whatever is left over. It also gives you permission to spend on wants. A budget that bans all enjoyment rarely survives the first month, while one that sets aside 30% for things you value is much easier to stick to.
The rule is also a useful diagnostic. Even if you never follow it exactly, comparing your real spending with 50/30/20 quickly shows where things are out of balance, whether that’s rent eating too much of your income, a wants budget that has quietly grown to 45%, or savings that never seem to happen. Our guide on how to track expenses helps you get the real numbers for that comparison.
The 50%: Needs
Needs are expenses you must pay to live and work, and that would cause serious problems if you skipped them. For most Indian households, they include rent or home loan EMIs, society maintenance, groceries and basic household supplies, electricity, water, cooking gas, mobile and internet plans, commuting costs, school fees, health and term insurance premiums, essential medicines, and the minimum payments due on any loans or credit cards.
A practical test, as summarised by reviewers of Warren and Tyagi’s book, is whether you could postpone the expense for several months without serious consequences. If not, it’s probably a need. Notice that “need” refers to the basic version of something: groceries are a need, but premium imported items are partly a want, and a phone plan is a need while the latest flagship phone on EMI is mostly a want.
The 30%: Wants
Wants are the things that make life enjoyable but that you could cut back on if you had to. Typical examples include eating out and food delivery, OTT and music subscriptions, clothes beyond the basics, gadgets, hobbies, weekend outings, vacations, gym memberships, salon visits and gifts beyond what’s expected. Upgrades also count, such as a bigger flat than you need, a car when public transport would work, or a premium phone plan.
The 30% isn’t a target you have to spend. It’s a ceiling that lets you enjoy your money without guilt while protecting your savings. If you’re happy spending less on wants, move the difference to savings, which is exactly how many people reach their goals faster. Our guide to smart spending habits shows how to get more enjoyment from the same wants budget.
The 20%: Savings and Debt Repayment
The final 20% goes towards your future. In order of priority for most people, that means building an emergency fund, paying down high-interest debt such as credit card balances and personal loans beyond the minimum, and then investing for long-term goals such as a home, children’s education and retirement through options like SIPs in mutual funds, PPF and NPS. Our emergency fund guide and SIP investment guide explain the first and last of these in detail.
A common question in India is whether EPF counts. Because the rule uses take-home pay, your EPF contribution is already deducted before the calculation, so it’s effectively extra savings on top of the 20%. That’s a good thing, but don’t let it become a reason to skip voluntary saving, especially if your EPF contribution is small. If you prefer, you can calculate the rule on take-home pay plus EPF and count EPF inside the 20%; just be consistent.
Need or Want? The Grey Areas
Some expenses don’t fit neatly into one bucket, and that’s where most people get stuck. A good approach is to split them: count the basic version as a need and anything above it as a want. The table below shows how to think about common Indian grey areas.
| Expense | Need Portion | Want Portion |
|---|---|---|
| Mobile phone and plan | A working phone and a basic plan | Flagship phone EMI, premium plan add-ons |
| Groceries | Staples, vegetables, basic household items | Premium brands, imported snacks, frequent quick-commerce top-ups |
| House help | Help essential for a working household or elderly care | Additional services for convenience |
| Car | Essential commuting where no practical alternative exists | A bigger or newer car than needed |
| Gym or fitness | Basic activity, such as walking or home workouts | Premium gym membership or classes |
| Festivals and weddings | Expected family obligations | Gifts, outfits and travel beyond the essentials |
| Rent | A home that meets your needs and commute | Extra space, location premium or amenities |
Be honest rather than generous with yourself when deciding. If almost everything ends up labelled as a need, look again at the table, because the extra portion of many needs is where savings are hiding.
50/30/20 Examples on Indian Salaries
Here’s how the 50/30/20 rule divides different monthly take-home salaries. These are simple calculations for illustration; your actual needs depend on your city, family size and commitments.
| Monthly Take-Home | Needs (50%) | Wants (30%) | Savings (20%) |
|---|---|---|---|
| ₹30,000 | ₹15,000 | ₹9,000 | ₹6,000 |
| ₹60,000 | ₹30,000 | ₹18,000 | ₹12,000 |
| ₹1,20,000 | ₹60,000 | ₹36,000 | ₹24,000 |
Take Ananya, a 26-year-old in Pune with a take-home salary of ₹60,000. Her needs are rent of ₹16,000, groceries and household supplies of ₹6,000, utilities and phone of ₹2,500, transport of ₹2,500 and insurance premiums of ₹2,000, for a total of ₹29,000, just under 50%. She caps wants at ₹18,000, covering eating out, OTT, shopping and weekend trips, and automates ₹12,000 of savings on salary day: ₹5,000 to her emergency fund until it reaches six months of expenses, and ₹7,000 into an equity SIP. Ananya is a composite example rather than a real person, but her numbers show how the rule works in practice.
At higher incomes, the 50% for needs often becomes easier to stay within, which is exactly when lifestyle inflation tempts people to upgrade everything. Many high earners choose to save well above 20%, as our guides on how to build wealth and the FIRE movement discuss.
When Needs Take More Than 50%
In many Indian cities, especially for young professionals, rent alone can take 30 to 40% of take-home pay, and a family with a home loan EMI, school fees and elderly parents’ medical costs may find needs well above 50%. National data shows how much basics weigh on budgets: the Household Consumption Expenditure Survey 2023-24 found that food alone accounted for about 47% of average consumption spending in rural India and about 40% in urban India.
If your needs exceed 50%, don’t abandon the rule. First, protect your savings: keep at least 10% going, even if you can’t manage 20% yet. Second, shrink wants temporarily to balance the books. Third, look for ways to reduce needs over time, such as sharing a flat, moving closer to work, refinancing a high-interest loan, or reviewing insurance, phone and utility costs. Our guides on how to reduce expenses and reducing household expenses have practical ideas, and growing your income, covered in our guide on how to increase income, often makes the biggest difference.
Variations of the 50/30/20 Rule
The exact percentages matter less than the principle of deciding your split in advance. These variations adapt the idea to different situations.
| Split | Needs / Wants / Savings | Best For |
|---|---|---|
| 50/30/20 | 50% / 30% / 20% | Moderate cost of living; balanced goals |
| 60/20/20 | 60% / 20% / 20% | High-rent cities; keeps savings at 20% by cutting wants |
| 70/20/10 | 70% / 20% / 10% | Tight budgets or heavy EMIs; a temporary starting point |
| 50/20/30 | 50% / 20% / 30% | Aggressive savers prioritising goals or debt payoff |
| 80/20 | Spend 80% / Save 20% | People who dislike splitting needs and wants |
Whichever split you choose, review it every six to twelve months. As your income grows or your EMIs end, move towards a higher savings rate rather than letting spending absorb the difference. Our guide on setting financial goals helps you decide what that extra saving should achieve.
How to Start Using the 50/30/20 Rule
Getting started takes about an hour. Follow these steps in order, and expect to fine-tune the numbers over the first two or three months.
- Find your take-home pay: Use the amount credited to your bank account each month. If your income varies, use a typical lean month.
- Calculate your three targets: Multiply take-home pay by 0.5, 0.3 and 0.2.
- List last month’s spending: Use bank statements and UPI history, and sort each expense into needs, wants or savings.
- Compare and adjust: See where you’re over or under each target, and decide what to change first.
- Automate the 20%: Set up a standing instruction and SIPs for the day after salary credit, so savings happen first.
- Review weekly: Spend ten minutes checking your wants spending so you can adjust before the month ends.
A budgeting app can do most of the sorting for you; our comparison of the best budgeting apps and the best apps to save money can help you choose. Some people find it easiest to use separate bank accounts for needs, wants and savings, so each bucket’s balance is visible at a glance.
Couples and families can apply the same rule to combined take-home income, with a shared account for household needs and individual allowances for personal wants. Agreeing on what counts as a need is the most important conversation, as our relationships section discusses.
Pros, Limitations and Common Mistakes
The rule’s biggest strengths are simplicity, flexibility and the fact that it makes saving automatic and spending guilt-free. Its main limitations are that 50% for needs is unrealistic for many people in expensive cities, that 20% savings may not be enough for late starters or those with big goals such as early retirement, and that it doesn’t tell you how to divide the 20% between emergency funds, debt and investing. It’s a starting framework, not a complete financial plan, which is where a broader financial planning guide helps.
Common mistakes include calculating percentages on gross salary or CTC instead of take-home pay, labelling wants as needs, treating the 30% as money that must be spent, forgetting annual expenses such as insurance renewals and festivals, and counting only minimum credit card payments while the balance grows. High-interest debt should usually be cleared before investing, as our guides on becoming debt-free and credit card tips explain. Small habits such as weekly meal planning, from our meal prep guide, make staying within the needs and wants limits much easier.
Try This Today: Write down your take-home pay and multiply it by 0.5, 0.3 and 0.2. Then add up last month’s spending in each bucket using your bank and UPI history. Whatever the gap, set up one change today, such as a standing instruction for your savings amount on the day after salary credit.
Frequently Asked Questions
1. What is the 50/30/20 rule in simple words?
It’s a budgeting guideline that splits your take-home pay into 50% for needs, 30% for wants and 20% for savings and extra debt repayment. It was popularised by Elizabeth Warren and Amelia Warren Tyagi in their 2005 book All Your Worth.
2. Is the 50/30/20 rule based on gross or net salary?
It’s based on take-home pay, after taxes and deductions. For salaried Indians, that’s the amount credited to your bank account, not your CTC or gross salary.
3. Where do EMIs and credit card payments go in the 50/30/20 rule?
Minimum payments on loans and credit cards count as needs, because you must pay them. Any extra amount you pay to clear debt faster counts in the 20% savings and debt repayment bucket.
4. What if my rent and needs are more than 50% of my salary?
Use a temporary split such as 60/20/20 or 70/20/10, keep at least 10% going to savings, cut wants first, and look for ways to lower fixed costs or raise income over time. Move back towards 20% savings as soon as you can.
5. Is saving 20% enough?
For many people, 20% is a solid start, especially early in their careers. Late starters, people with large goals such as early retirement, or those without employer retirement benefits may need to save more.
Conclusion
The 50/30/20 rule is one of the simplest ways to bring balance to your money: half of your take-home pay for needs, 30% for wants and 20% for your future. Its real value lies in deciding your split in advance and automating savings, not in hitting the percentages exactly. Adapt it to your city and stage of life, use variations such as 60/20/20 when needs are high, and raise your savings rate as your income grows.
Once your split is working, the next step is making your 20% work harder, which our guides on investing for beginners and retirement planning basics cover. Feeling in control of your money also reduces everyday stress, which supports our guide to lifestyle changes that improve your health.
Related Reading
- How to Save Money Fast
- Money Saving Challenges
- Best Financial Habits
- Personal Finance Mistakes to Avoid
Sources and Further Reading
This guide was last reviewed on October 5, 2026. It provides general information for educational purposes and is not personalised financial, tax or investment advice. Consider consulting a SEBI-registered investment adviser or a qualified financial planner for decisions specific to your situation.
- Warren, E., & Warren Tyagi, A. (2005). All Your Worth: The Ultimate Lifetime Money Plan. Free Press. Summary and review via Get Rich Slowly
- Ministry of Statistics and Programme Implementation. Household Consumption Expenditure Survey: 2023-24 (press release). pib.gov.in